
The Billion-Dollar Clean Energy Hardware Play
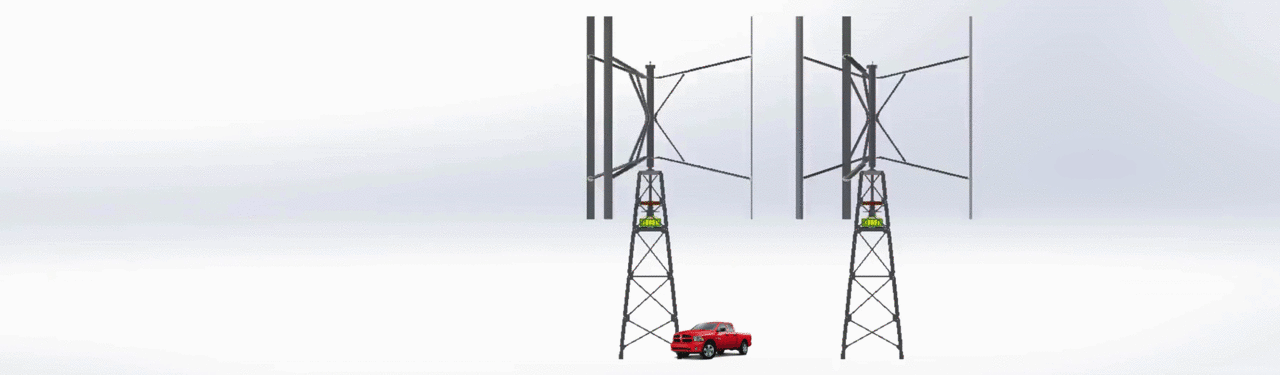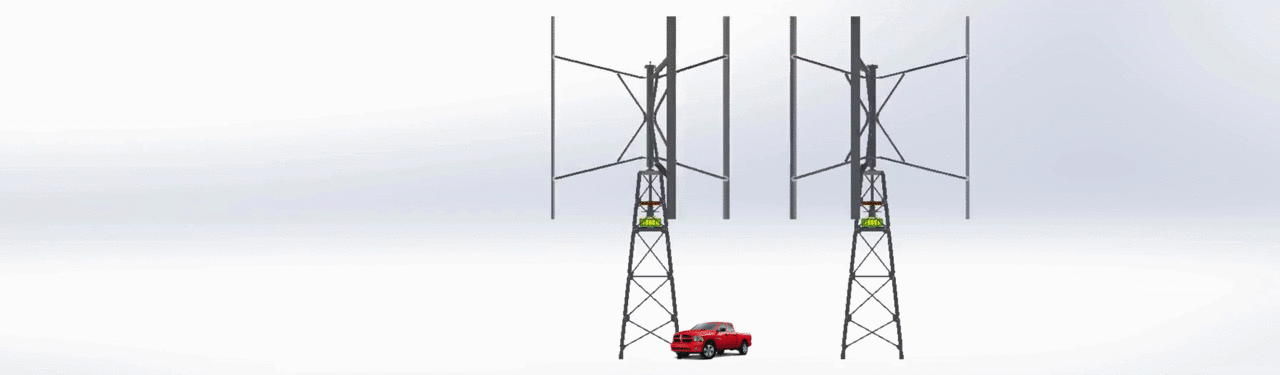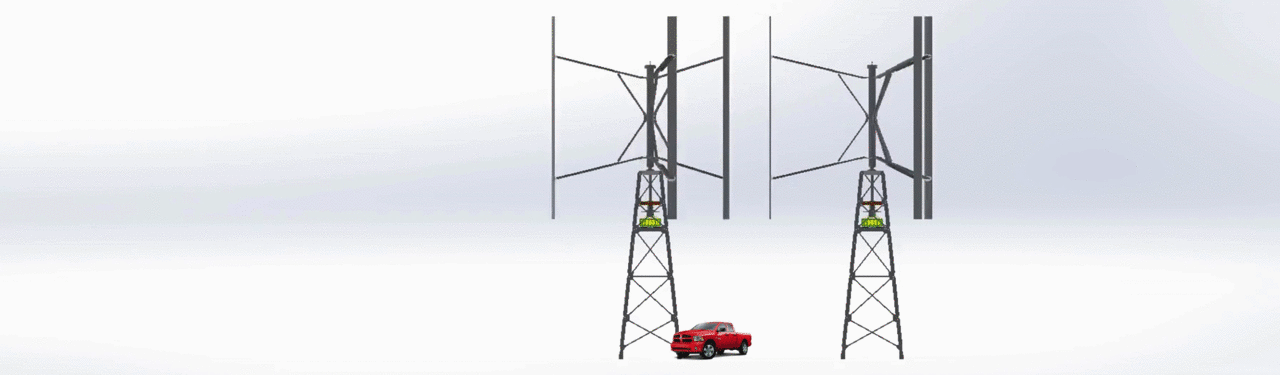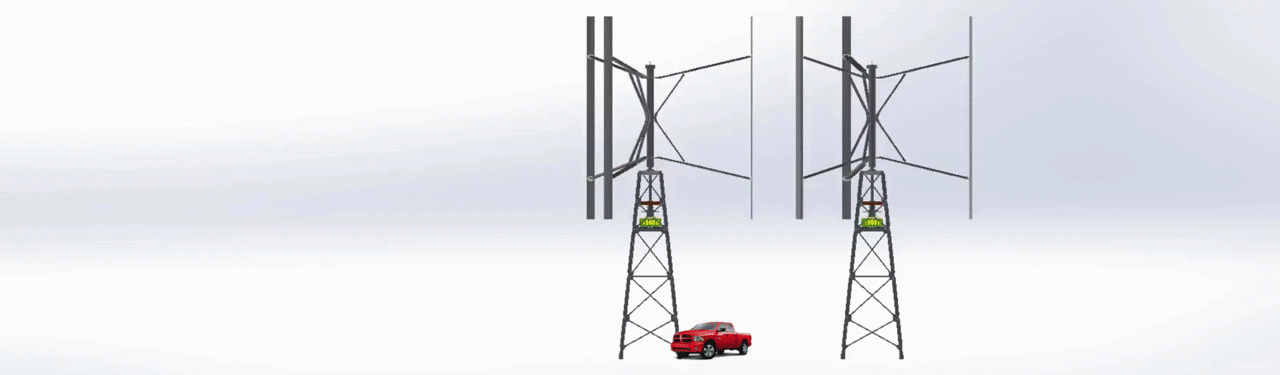 Building an industrial clean energy company is very different from launching a consumer app or a gadget. At Wind Harvest, we are building infrastructure—utility-scale equipment that has to run for decades, survive harsh environments, satisfy regulators, and deliver power at a cost that beats fossil and other competitors.
That takes years of R&D, engineering, field trials, certification, and project development before a single large contract is signed. It also takes patient capital.
And yet, this is exactly how many of the most valuable climate companies were built: First Solar, Tesla, Ormat, Enphase, Bloom Energy, Plug Power, ChargePoint, and a new generation of geothermal and hydrogen players like Fervo Energy—all of them spent years in the wilderness before becoming multi-billion-dollar companies or high-profile IPOs and acquisitions.
Wind Harvest isn’t claiming that it will do as well as these other companies but it has completed all but two of the commercialization steps. With funding from this round, the Company can complete third party certification and complete the process of advancing projects to the point where they can secure financing and order Wind Harvesters.
Hardware for the energy transition is a long game—but when it works, it creates generational value.
Where the Money Goes
As you read about the successful cleantech and renewable energy startups below, keep in mind the following:
- ~$18M has been invested in Wind Harvest.
- Once had our Series A round in 2012, we invested about $2M and 2-3 years for each Technology Readiness Level that a prototype advanced through.
- Because we don’t need our own factories to make Wind Harvester components, we are an “asset light” company that should not need the levels of capital used by these other startups before they became liquid.
- We have spent years working on developing projects that will buy our turbines. We aim to achieve positive cash flow by 2027, based on our current financial projections, though this is subject to various risks and uncertainties.
- Most of the capital we plan on raising after this StartEngine round will be used as working capital to finance and develop projects in our pipeline
For industrial clean-tech, capital is concentrated in three areas:
1. Product & Project Development
- Designing, prototyping, and testing full-scale systems (turbines, fuel cells, power blocks, inverters, EV chargers).
- Certification and standards compliance (IEC 61400, UL/IEEE, grid interconnection, safety codes, marine/coastal standards, seismic and hurricane ratings, etc.).
- Pilots and demonstration projects with utilities, data centers, industrials, ports, and IPPs.
This stage is long and expensive. Compared to some hugely successful companies in the renewable energy industrial scale hardware space, the ~$18M invested in Wind Harvest is small.
Before First Solar went public in November 2006, it raised approximately $100 million in private funding. The IPO itself raised about $400 million. Founded initially as Solar Cells, Inc. in 1990 and rebranded to First Solar, Inc. in 1999 after being purchased by True North Partners, LLC, the company took several years to develop its thin-film photovoltaic technology and scale manufacturing. By the time of its IPO in 2006, First Solar had grown revenues to over $135 million and was already profitable, marking a strong milestone supported by significant early-stage investment focused on R&D, scale-up, and market development. (Wikipedia)
Bloom Energy raised approximately $1.3 to $1.4 billion in private funding before its initial public offering (IPO) in July 2018. The IPO itself raised about $270 million. Founded in 2001, Bloom Energy spent many years developing its solid oxide fuel cell technology and building commercial deployments before going public 17 years later. Major investors included Kleiner Perkins, Canada Pension Plan Investment Board, and several sovereign wealth funds. At the time of IPO, the company had a market capitalization of approximately $1.6 billion and substantial backing from large institutional investors. (Wikipedia)
2. Manufacturing & Supply Chain
- Building or contracting factories that can deliver bankable, repeatable product at scale.
- Setting up tooling, molds, test rigs, and QA systems.
- Securing suppliers for steel, power electronics, composites, catalysts, and other long-lead components.
Ormat’s geothermal and recovered-energy plants, for example, sit on decades of supply-chain development; the company was founded in 1965, then completed a U.S. IPO in 2004 to scale its geothermal fleet worldwide. (Wikipedia)
3. Commercialization & Working Capital
- Utility and corporate sales cycles often run 18–36 months and involve pilots, bankability studies, and project finance.
- Inventory of major components (turbines, inverters, stacks, chargers) must be funded months before revenue.
- Project-level equity and development spend must be advanced well before long-term offtake or tax equity closes.
ChargePoint was founded in 2007 and just prior to the SPAC deal, it raised $127 million in private funding at a post-money valuation of around $1.58 billion. ChargePoint built out a large base of enterprise and fleet customers, then went public via a SPAC transaction in 2021 at an implied $2.4 billion enterprise value, to keep scaling its charging network and hardware/software platform. (investors.chargepoint.com)
This combination—deep technology, heavy equipment, long sales cycles—makes industrial climate hardware capital-intensive. But it is also what builds defensible moats and high-value exits.
Why It’s Worth It
Once a startup solves the hard problems—make the hardware work, prove it in the field, certify it, and integrate it with grid and customer systems—they’re no longer just selling equipment. They are building critical infrastructure.
That’s when:
- Utilities and corporates fold their technology into multi-decade resource plans.
- Data centers, refineries, ports, logistics firms, and large commercial customers adopt their systems at multiple sites.
- Project finance, tax equity, and infrastructure funds start underwriting their technology as “bankable.”
This is the point where companies like First Solar, Tesla, Ormat, Enphase, Bloom, Plug, and ChargePoint turned years of R&D and losses into enduring equity value and, in many cases, billion-dollar or trillion-dollar valuations. (StockAnalysis)
Examples From Industrial Clean Tech
Photovoltaics & Power Electronics
First Solar (utility-scale PV)
- Founded in 1999; focused on thin-film cadmium telluride modules for large solar plants. (Wikipedia)
- IPO in November 2006 on NASDAQ (FSLR), at ~$1.4 billion initial market cap. (Reuters)
- Today: a leading U.S. solar manufacturer with multiple U.S. factories and more than 14 GW of expected domestic capacity by 2026. (Wikipedia)
Enphase Energy (micro-inverters & storage)
- Founded in 2006, commercialized module-level micro-inverters used by residential and commercial installers worldwide. (Wikipedia)
- IPO in 2012 on NASDAQ (ENPH). (CleanTechnica)
- Has since become a multi-billion-dollar public company and a key player in distributed solar and storage. (DCF Modeling)
Mobility & Electrification
Tesla (EVs, battery storage, solar)
- Founded in 2003 by Martin Eberhard and Marc Tarpenning, initially focused on an electric sports car and then full EV platforms. (Wikipedia)
- IPO on June 29, 2010 at $17/share, raising about $226 million—Tesla’s first major liquidity event. (WIRED)
- Since then, Tesla has become one of the world’s most valuable companies, periodically exceeding $1 trillion in market capitalization, driven by EVs, grid-scale storage, and solar. (Wikipedia)
Fuel Cells & Hydrogen
Plug Power (hydrogen fuel cells)
- Founded in 1997 to develop fuel cells for material-handling equipment and stationary power. (Wikipedia)
- IPO in 1999, one of the early clean-tech listings. (Wikipedia)
- Now a public company building green hydrogen plants and fuel cell systems for vehicles and industry, backed by a recent $1.66 billion DOE loan guarantee and ongoing equity raises. (Times Union)
Geothermal & Advanced Geothermal
Fervo Energy (enhanced geothermal)
- Founded in 2017 to apply horizontal drilling and fiber-optic monitoring to geothermal.
- Reached a $1.02 billion valuation in 2024 and is actively preparing for a potential IPO in 2026–27, targeting a $2–4 billion valuation range. (Axios)
These stories show the same pattern: industrial-scale hardware, long development cycles, and then major liquidity events—IPOs, acquisitions, and large valuations—once the technology is proven and markets mature.
Where Our Company Fits In
Like these companies, Wind Harvest is building industrial-grade clean energy hardware designed for long-term operation in demanding environments and for large-ticket sales to utilities, IPPs, corporates, and infrastructure owners—not consumer products.
We are following the same proven path that took First Solar from a thin-film science project to a global manufacturer, that took Tesla from a prototype Roadster to a trillion-dollar EV and storage leader, and that is now carrying companies like Bloom, Ormat, Enphase, Plug, ChargePoint, and Fervo into the heart of the energy transition. (StockAnalysis)
The Investor Opportunity
Investing in industrial clean-tech hardware is not about chasing the next social app. It’s about owning part of the infrastructure that will power, move, and heat the 21st-century economy.
- The time and capital required to build these systems create high barriers to entry.
- Once scaled and de-risked, these platforms can become core assets in power grids, mobility systems, and industrial energy use.
- As the examples above show, this is where large exits, IPOs, and long-term valuations have historically emerged.
By backing us now, you’re funding the stage between technical breakthrough and market dominance—the same stretch of road where Tesla, First Solar, Ormat, Enphase, Bloom, Plug, ChargePoint, and Fervo converted deep engineering work into enduring enterprise value.
And just like them, we know: in clean energy hardware, it’s a marathon, not a sprint—but the finish line can be worth billions.
This Reg CF offering is made available through StartEngine Primary, LLC. This investment is speculative, illiquid, and involves a high degree of risk, including the possible loss of your entire investment.
Contact: Jake Weatherman, Blog Supervisor – jweatherman@windharvest.com
Wind Harvest International, Inc. is a California-based renewable energy technology company, founded in 2006. The company makes, sells, and develops projects for its Wind Harvester brand of H-type turbines, the only known product designed to harvest the highly energetic, turbulent wind that blows 15-80 feet above the ground.


